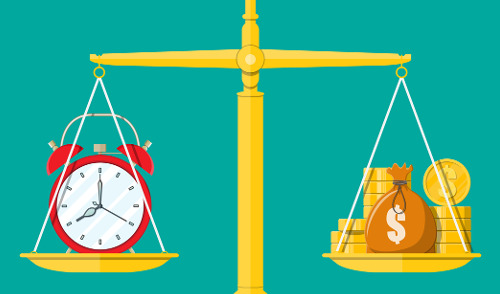
No matter what decision is made – is the life annuity option ever worth it? The biggest problem with purchasing the annuity is that it is irrevocable and as it is a single-premium immediate annuity, you cannot surrender the contract down the road. By sacrificing flexibility, however, what you gain is certainty. The annuity will have a fixed growth amount (usually between 2% and 3%) and the annuitant will receive a fixed dollar amount for their lifetime, typically on a monthly basis.
Installment payments on the other hand can be increased, decreased, or stopped. The money also stays in the TSP, where it can continue to grow in the core funds (G, F, C, S, and I). This also means the option to withdraw one-time lump sums remains on the table should you decide to move all or any of the TSP money into an outside account.
As for annuities overall, they’re usually overpriced and overcomplicated, which makes them easy to sell. Certainty can also be appealing to some folks. That being said, if the MetLife annuity seems unappealing, it is possible to withdraw the funds from the TSP and purchase another annuity product elsewhere. But whatever you choose, this decision is one of the most important when retiring from federal service and why you need the most crucial component to a comfortable federal retirement: strategy.
—-
Until Next Time,
The information has been obtained from sources considered reliable but we do not guarantee that the foregoing material is accurate or complete. Any opinions are those of Serving Those Who Serve writers and not necessarily those of RJFS or Raymond James. Any information is not a complete summary or statement of all available data necessary for making an investment decision and does not constitute a recommendation. Investing involves risk and you may incur a profit or loss regardless of strategy suggested. Every investor’s situation is unique and you should consider your investment goals, risk tolerance, and time horizon before making any investment or financial decision. Prior to making an investment decision, please consult with your financial advisor about your individual situation. While we are familiar with the tax provisions of the issues presented herein, as Financial Advisors of RJFS, we are not qualified to render advice on tax or legal matters. You should discuss tax or legal matters with the appropriate professional. **
Should you choose the TSP life annuity option? What is it? What are the pros and cons?
Upon retirement, federal employees under FERS can expect monthly income streams from their pension, social security benefits, and the Thrift Savings Plan (TSP). While the FERS annuity and social security amounts are pretty much fixed (although they usually see a pay bump due to annual COLAs), the TSP is a different monster altogether.
Recent federal retirees can select installment payments, a MetLife annuity, or they can withdraw their money and move it to an outside retirement account (IRA) and have a financial planner manage their investments and income. It doesn’t have to be an “all or nothing” decision, though. Federal annuitants have the option to use a portion of their TSP balance to purchase an annuity from MetLife and then they can withdraw all of the remaining portion, or set up installment payments with their remaining TSP balance.
No matter what decision is made – is the life annuity option ever worth it? The biggest problem with purchasing the annuity is that it is irrevocable and as it is a single-premium immediate annuity, you cannot surrender the contract down the road. By sacrificing flexibility, however, what you gain is certainty. The annuity will have a fixed growth amount (usually between 2% and 3%) and the annuitant will receive a fixed dollar amount for their lifetime, typically on a monthly basis.
Installment payments on the other hand can be increased, decreased, or stopped. The money also stays in the TSP, where it can continue to grow in the core funds (G, F, C, S, and I). This also means the option to withdraw one-time lump sums remains on the table should you decide to move all or any of the TSP money into an outside account.
As for annuities overall, they’re usually overpriced and overcomplicated, which makes them easy to sell. Certainty can also be appealing to some folks. That being said, if the MetLife annuity seems unappealing, it is possible to withdraw the funds from the TSP and purchase another annuity product elsewhere. But whatever you choose, this decision is one of the most important when retiring from federal service and why you need the most crucial component to a comfortable federal retirement: strategy.
—-
Until Next Time,
The information has been obtained from sources considered reliable but we do not guarantee that the foregoing material is accurate or complete. Any opinions are those of Serving Those Who Serve writers and not necessarily those of RJFS or Raymond James. Any information is not a complete summary or statement of all available data necessary for making an investment decision and does not constitute a recommendation. Investing involves risk and you may incur a profit or loss regardless of strategy suggested. Every investor’s situation is unique and you should consider your investment goals, risk tolerance, and time horizon before making any investment or financial decision. Prior to making an investment decision, please consult with your financial advisor about your individual situation. While we are familiar with the tax provisions of the issues presented herein, as Financial Advisors of RJFS, we are not qualified to render advice on tax or legal matters. You should discuss tax or legal matters with the appropriate professional. **
Should you choose the TSP life annuity option? What is it? What are the pros and cons?
Upon retirement, federal employees under FERS can expect monthly income streams from their pension, social security benefits, and the Thrift Savings Plan (TSP). While the FERS annuity and social security amounts are pretty much fixed (although they usually see a pay bump due to annual COLAs), the TSP is a different monster altogether.
Recent federal retirees can select installment payments, a MetLife annuity, or they can withdraw their money and move it to an outside retirement account (IRA) and have a financial planner manage their investments and income. It doesn’t have to be an “all or nothing” decision, though. Federal annuitants have the option to use a portion of their TSP balance to purchase an annuity from MetLife and then they can withdraw all of the remaining portion, or set up installment payments with their remaining TSP balance.
No matter what decision is made – is the life annuity option ever worth it? The biggest problem with purchasing the annuity is that it is irrevocable and as it is a single-premium immediate annuity, you cannot surrender the contract down the road. By sacrificing flexibility, however, what you gain is certainty. The annuity will have a fixed growth amount (usually between 2% and 3%) and the annuitant will receive a fixed dollar amount for their lifetime, typically on a monthly basis.
Installment payments on the other hand can be increased, decreased, or stopped. The money also stays in the TSP, where it can continue to grow in the core funds (G, F, C, S, and I). This also means the option to withdraw one-time lump sums remains on the table should you decide to move all or any of the TSP money into an outside account.
As for annuities overall, they’re usually overpriced and overcomplicated, which makes them easy to sell. Certainty can also be appealing to some folks. That being said, if the MetLife annuity seems unappealing, it is possible to withdraw the funds from the TSP and purchase another annuity product elsewhere. But whatever you choose, this decision is one of the most important when retiring from federal service and why you need the most crucial component to a comfortable federal retirement: strategy.
—-
Until Next Time,
The information has been obtained from sources considered reliable but we do not guarantee that the foregoing material is accurate or complete. Any opinions are those of Serving Those Who Serve writers and not necessarily those of RJFS or Raymond James. Any information is not a complete summary or statement of all available data necessary for making an investment decision and does not constitute a recommendation. Investing involves risk and you may incur a profit or loss regardless of strategy suggested. Every investor’s situation is unique and you should consider your investment goals, risk tolerance, and time horizon before making any investment or financial decision. Prior to making an investment decision, please consult with your financial advisor about your individual situation. While we are familiar with the tax provisions of the issues presented herein, as Financial Advisors of RJFS, we are not qualified to render advice on tax or legal matters. You should discuss tax or legal matters with the appropriate professional. **
Should you choose the TSP life annuity option? What is it? What are the pros and cons?
Upon retirement, federal employees under FERS can expect monthly income streams from their pension, social security benefits, and the Thrift Savings Plan (TSP). While the FERS annuity and social security amounts are pretty much fixed (although they usually see a pay bump due to annual COLAs), the TSP is a different monster altogether.
Recent federal retirees can select installment payments, a MetLife annuity, or they can withdraw their money and move it to an outside retirement account (IRA) and have a financial planner manage their investments and income. It doesn’t have to be an “all or nothing” decision, though. Federal annuitants have the option to use a portion of their TSP balance to purchase an annuity from MetLife and then they can withdraw all of the remaining portion, or set up installment payments with their remaining TSP balance.
No matter what decision is made – is the life annuity option ever worth it? The biggest problem with purchasing the annuity is that it is irrevocable and as it is a single-premium immediate annuity, you cannot surrender the contract down the road. By sacrificing flexibility, however, what you gain is certainty. The annuity will have a fixed growth amount (usually between 2% and 3%) and the annuitant will receive a fixed dollar amount for their lifetime, typically on a monthly basis.
Installment payments on the other hand can be increased, decreased, or stopped. The money also stays in the TSP, where it can continue to grow in the core funds (G, F, C, S, and I). This also means the option to withdraw one-time lump sums remains on the table should you decide to move all or any of the TSP money into an outside account.
As for annuities overall, they’re usually overpriced and overcomplicated, which makes them easy to sell. Certainty can also be appealing to some folks. That being said, if the MetLife annuity seems unappealing, it is possible to withdraw the funds from the TSP and purchase another annuity product elsewhere. But whatever you choose, this decision is one of the most important when retiring from federal service and why you need the most crucial component to a comfortable federal retirement: strategy.
—-
Until Next Time,
The information has been obtained from sources considered reliable but we do not guarantee that the foregoing material is accurate or complete. Any opinions are those of Serving Those Who Serve writers and not necessarily those of RJFS or Raymond James. Any information is not a complete summary or statement of all available data necessary for making an investment decision and does not constitute a recommendation. Investing involves risk and you may incur a profit or loss regardless of strategy suggested. Every investor’s situation is unique and you should consider your investment goals, risk tolerance, and time horizon before making any investment or financial decision. Prior to making an investment decision, please consult with your financial advisor about your individual situation. While we are familiar with the tax provisions of the issues presented herein, as Financial Advisors of RJFS, we are not qualified to render advice on tax or legal matters. You should discuss tax or legal matters with the appropriate professional. **
The FedLife Podcast is your in-depth, biweekly deep dive into the world of federal benefits and retirement planning. Hosted by federal benefits expert Ed Zurndorfer and Dan Sipe of Serving Those Who Serve, each 30-minute episode unpacks the complexities of FERS and CSRS retirement, FEHB and Medicare, survivor benefits, tax planning, and more. Designed for federal employees and retirees who want more than just the basics, FedLife goes beyond the headlines to explore the rules, nuances, and strategies that can make a meaningful difference in your retirement. Remember: it’s your Fed life, make it a great one.
The Fed15 Podcast is your weekly 15(ish)-minute briefing on federal benefits and financial planning, built specifically for federal employees and retirees. Hosted by Dan Sipe and Katelyn Murray of Serving Those Who Serve, each episode delivers clear, actionable guidance on topics like FERS and CSRS retirement, TSP strategies, FEHB, survivor benefits, tax planning, and more! Whether you’re five years from retirement or already there, The Fed15 helps you cut through the noise, avoid costly mistakes, and make confident decisions about your federal benefits.