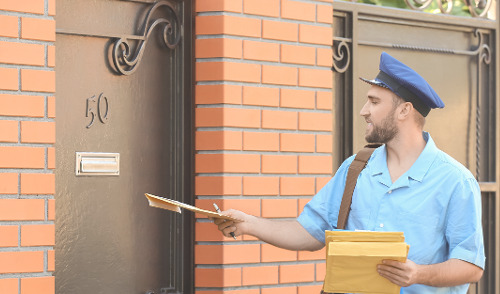
Postal workers will keep their existing FEHB plan until the end of 2024, which is when they will need to select a new PSHB plan during open season. However, each FEHB policy that currently covers at least 1,500 USPS employees (as of January 31, 2023) is supposed to be offered in the PSHB program as well. If eligible USPS workers don’t choose a new PSHB plan, and their current FEHB plan is not offered in the PSHB marketplace, they will be auto-enrolled in a similar PSHB policy from the same insurance provider. If that provider does not offer any plans in the new PSHB program, they will be automatically signed up for the lowest cost, non-high deductible, nationwide plan that does not require a membership fee.
An obvious difference between PSHB and FEHB is that they won’t offer the exact same plans, although there will definitely be some overlap. Some postal health plans might be offered by providers who don’t participate in FEHB, and vice versa. But it really isn’t the plans themselves that will save the USPS over $10 billion from switching to PSHB. The biggest change is that going forward, all USPS employees and retirees will be required to enroll in Medicare B once they turn 65 years old. If you turn 64 before 2025, then you’ll dodge the Medicare B requirement but will still have to switch your coverage from FEHB to the new PSHB program.
OPM, the agency that has been tasked to create a new digital marketplace and infrastructure for the new PSHB program, is busy with other IT modernization projects, but calls PSHB a “major initiative.” The Medicare B requirement also comes into play here, as OPM’s Chief Information Officer noted one of the more difficult aspects of creating the PSHB system is that it will have to verify that enrollees are also enrolled in Medicare part B.
—-
Until Next Time,
The information has been obtained from sources considered reliable but we do not guarantee that the foregoing material is accurate or complete. Any opinions are those of Serving Those Who Serve writers and not necessarily those of RJFS or Raymond James. Any information is not a complete summary or statement of all available data necessary for making an investment decision and does not constitute a recommendation. Investing involves risk and you may incur a profit or loss regardless of strategy suggested. Every investor’s situation is unique and you should consider your investment goals, risk tolerance, and time horizon before making any investment or financial decision. Prior to making an investment decision, please consult with your financial advisor about your individual situation. While we are familiar with the tax provisions of the issues presented herein, as Financial Advisors of RJFS, we are not qualified to render advice on tax or legal matters. You should discuss tax or legal matters with the appropriate professional. **
OPM is scrambling to create a new health insurance marketplace for USPS workers, mandated by Congress to go live by 2025.
When the Postal Service Reform Act became law last year, it mandated that US postal workers will start utilizing a different insurance program than the Federal Employee Health Benefits (FEHB) program. Currently, USPS employees who are eligible for a health plan use the same marketplace for coverage as all such federal employees – the FEHB program. On January 1st, 2025 – USPS employees will only be eligible for plans offered in the upcoming Postal Service Health Benefits (PSHB) program. (Note: this does not affect FEDVIP or FEGLI coverage.)
Postal workers will keep their existing FEHB plan until the end of 2024, which is when they will need to select a new PSHB plan during open season. However, each FEHB policy that currently covers at least 1,500 USPS employees (as of January 31, 2023) is supposed to be offered in the PSHB program as well. If eligible USPS workers don’t choose a new PSHB plan, and their current FEHB plan is not offered in the PSHB marketplace, they will be auto-enrolled in a similar PSHB policy from the same insurance provider. If that provider does not offer any plans in the new PSHB program, they will be automatically signed up for the lowest cost, non-high deductible, nationwide plan that does not require a membership fee.
An obvious difference between PSHB and FEHB is that they won’t offer the exact same plans, although there will definitely be some overlap. Some postal health plans might be offered by providers who don’t participate in FEHB, and vice versa. But it really isn’t the plans themselves that will save the USPS over $10 billion from switching to PSHB. The biggest change is that going forward, all USPS employees and retirees will be required to enroll in Medicare B once they turn 65 years old. If you turn 64 before 2025, then you’ll dodge the Medicare B requirement but will still have to switch your coverage from FEHB to the new PSHB program.
OPM, the agency that has been tasked to create a new digital marketplace and infrastructure for the new PSHB program, is busy with other IT modernization projects, but calls PSHB a “major initiative.” The Medicare B requirement also comes into play here, as OPM’s Chief Information Officer noted one of the more difficult aspects of creating the PSHB system is that it will have to verify that enrollees are also enrolled in Medicare part B.
—-
Until Next Time,
The information has been obtained from sources considered reliable but we do not guarantee that the foregoing material is accurate or complete. Any opinions are those of Serving Those Who Serve writers and not necessarily those of RJFS or Raymond James. Any information is not a complete summary or statement of all available data necessary for making an investment decision and does not constitute a recommendation. Investing involves risk and you may incur a profit or loss regardless of strategy suggested. Every investor’s situation is unique and you should consider your investment goals, risk tolerance, and time horizon before making any investment or financial decision. Prior to making an investment decision, please consult with your financial advisor about your individual situation. While we are familiar with the tax provisions of the issues presented herein, as Financial Advisors of RJFS, we are not qualified to render advice on tax or legal matters. You should discuss tax or legal matters with the appropriate professional. **
OPM is scrambling to create a new health insurance marketplace for USPS workers, mandated by Congress to go live by 2025.
When the Postal Service Reform Act became law last year, it mandated that US postal workers will start utilizing a different insurance program than the Federal Employee Health Benefits (FEHB) program. Currently, USPS employees who are eligible for a health plan use the same marketplace for coverage as all such federal employees – the FEHB program. On January 1st, 2025 – USPS employees will only be eligible for plans offered in the upcoming Postal Service Health Benefits (PSHB) program. (Note: this does not affect FEDVIP or FEGLI coverage.)
Postal workers will keep their existing FEHB plan until the end of 2024, which is when they will need to select a new PSHB plan during open season. However, each FEHB policy that currently covers at least 1,500 USPS employees (as of January 31, 2023) is supposed to be offered in the PSHB program as well. If eligible USPS workers don’t choose a new PSHB plan, and their current FEHB plan is not offered in the PSHB marketplace, they will be auto-enrolled in a similar PSHB policy from the same insurance provider. If that provider does not offer any plans in the new PSHB program, they will be automatically signed up for the lowest cost, non-high deductible, nationwide plan that does not require a membership fee.
An obvious difference between PSHB and FEHB is that they won’t offer the exact same plans, although there will definitely be some overlap. Some postal health plans might be offered by providers who don’t participate in FEHB, and vice versa. But it really isn’t the plans themselves that will save the USPS over $10 billion from switching to PSHB. The biggest change is that going forward, all USPS employees and retirees will be required to enroll in Medicare B once they turn 65 years old. If you turn 64 before 2025, then you’ll dodge the Medicare B requirement but will still have to switch your coverage from FEHB to the new PSHB program.
OPM, the agency that has been tasked to create a new digital marketplace and infrastructure for the new PSHB program, is busy with other IT modernization projects, but calls PSHB a “major initiative.” The Medicare B requirement also comes into play here, as OPM’s Chief Information Officer noted one of the more difficult aspects of creating the PSHB system is that it will have to verify that enrollees are also enrolled in Medicare part B.
—-
Until Next Time,
The information has been obtained from sources considered reliable but we do not guarantee that the foregoing material is accurate or complete. Any opinions are those of Serving Those Who Serve writers and not necessarily those of RJFS or Raymond James. Any information is not a complete summary or statement of all available data necessary for making an investment decision and does not constitute a recommendation. Investing involves risk and you may incur a profit or loss regardless of strategy suggested. Every investor’s situation is unique and you should consider your investment goals, risk tolerance, and time horizon before making any investment or financial decision. Prior to making an investment decision, please consult with your financial advisor about your individual situation. While we are familiar with the tax provisions of the issues presented herein, as Financial Advisors of RJFS, we are not qualified to render advice on tax or legal matters. You should discuss tax or legal matters with the appropriate professional. **
The FedLife Podcast is your in-depth, biweekly deep dive into the world of federal benefits and retirement planning. Hosted by federal benefits expert Ed Zurndorfer and Dan Sipe of Serving Those Who Serve, each 30-minute episode unpacks the complexities of FERS and CSRS retirement, FEHB and Medicare, survivor benefits, tax planning, and more. Designed for federal employees and retirees who want more than just the basics, FedLife goes beyond the headlines to explore the rules, nuances, and strategies that can make a meaningful difference in your retirement. Remember: it’s your Fed life, make it a great one.
The Fed15 Podcast is your weekly 15(ish)-minute briefing on federal benefits and financial planning, built specifically for federal employees and retirees. Hosted by Dan Sipe and Katelyn Murray of Serving Those Who Serve, each episode delivers clear, actionable guidance on topics like FERS and CSRS retirement, TSP strategies, FEHB, survivor benefits, tax planning, and more! Whether you’re five years from retirement or already there, The Fed15 helps you cut through the noise, avoid costly mistakes, and make confident decisions about your federal benefits.